
Expansionary Fiscal Policy: Spending, Tax Cuts, and Growth Trade-Offs
Expansionary fiscal policy uses higher government spending, lower taxes, or increased transfers to support economic activity. The aim is to raise demand, protect incomes, and limit unemployment when the economy operates below its capacity. However, the result depends on timing, household behavior, project delivery, inflation pressures, and the government’s ability to finance the intervention.
Expansionary Fiscal Policy: What Changes in the Economy?
Governments can influence spending directly through purchases of goods and services. They can also change private budgets through tax reductions, rebates, or benefit payments. A construction contract creates demand for labor and materials, whereas a household rebate first changes disposable income. Consequently, identical budget costs do not guarantee identical economic effects.
Fiscal authorities authorize spending and taxation while central banks manage monetary conditions. These tools sometimes reinforce each other and sometimes conflict. Our comparison of fiscal and monetary policy explains how the two mechanisms interact.
A useful starting question is not simply, “How large is the stimulus package?” Instead, ask three questions: Who receives the money, when can they spend it, and what can the economy actually produce in response?
The Main Instruments: Spending, Taxes, and Transfers
Government purchases and public investment
Government purchases pay for current services, supplies, and public operations. For example, a public health authority may buy medical equipment or expand staffing. Those purchases immediately create demand for the providers able to supply them. However, higher orders can strain limited capacity if a sector already operates near its practical limits.
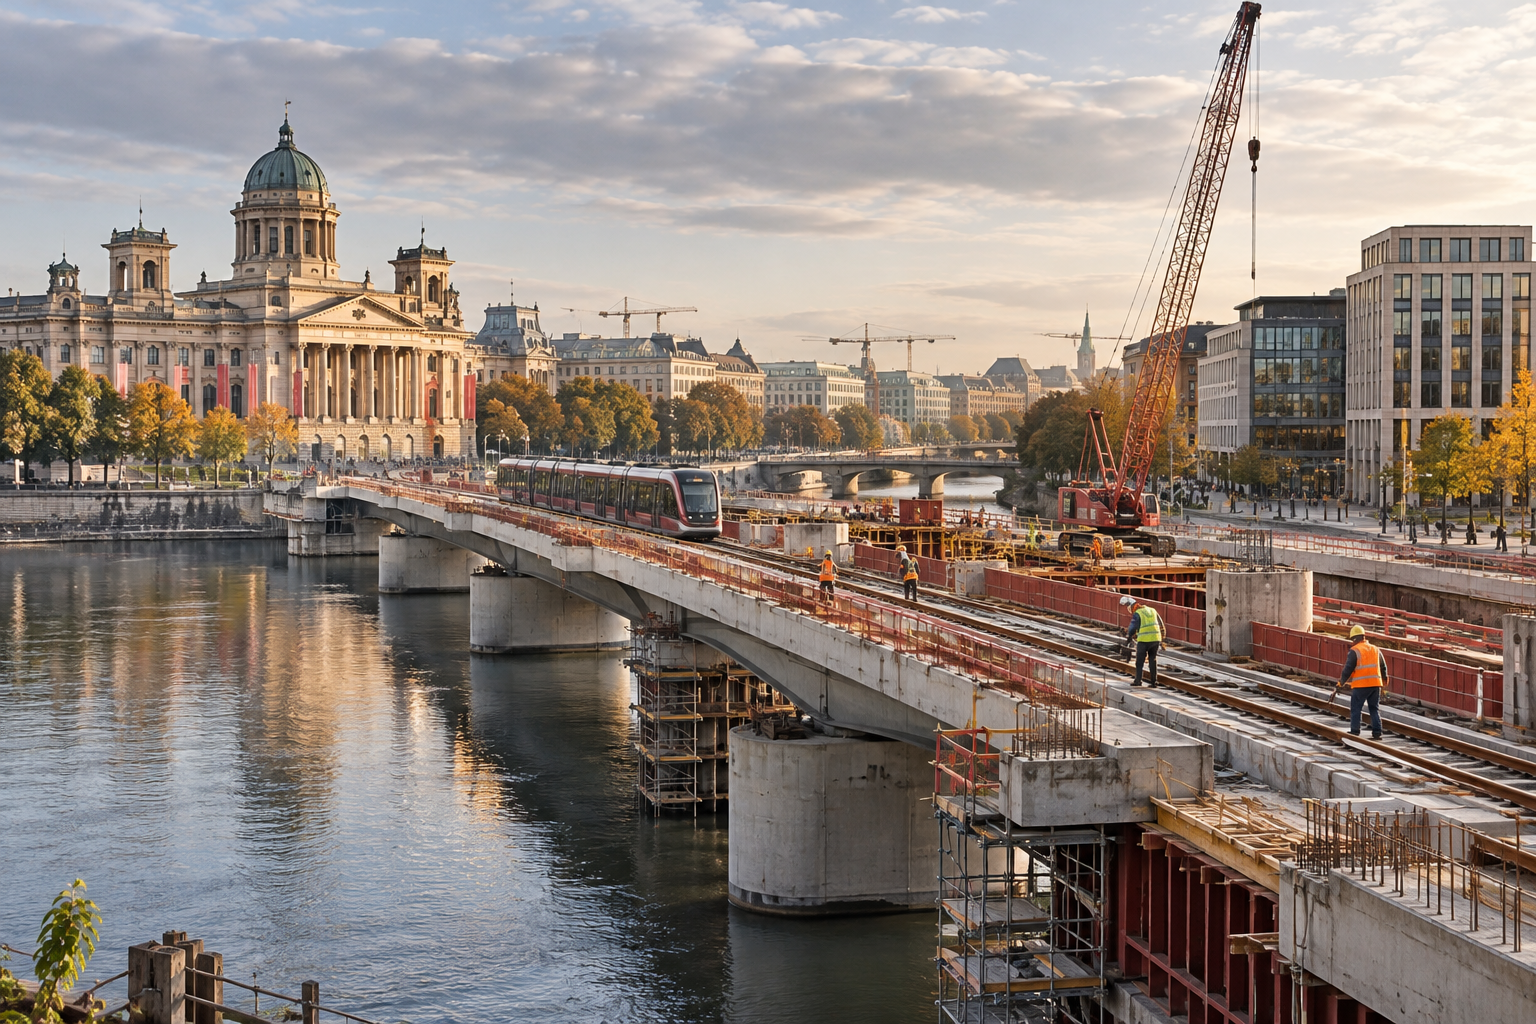
Meanwhile, public investment takes a longer view. A modernized port, electricity grid, rail connection, or water system may support demand during construction and improve productivity after completion. Yet financing approval is only the beginning. Procurement, permits, technical design, available workers, and construction schedules determine when the money reaches firms and households.
Therefore, a government that needs rapid stabilization should distinguish shovel-ready maintenance from an entirely new megaproject. The first may begin relatively soon; the second may deliver its largest benefits after the recession has ended. Both can be worthwhile, but they solve different timing problems.
Personal and business tax measures
A reduction in personal income taxes can leave employees with more take-home pay. A temporary rebate can provide cash to households affected by a downturn. Businesses may respond to tax allowances by bringing forward eligible investment, particularly when they already expect customer demand to recover.
However, a tax measure changes incentives and resources rather than purchasing output directly. Households worried about losing their jobs may save the additional money or repay debt. Likewise, firms with weak sales projections may ignore a temporary investment incentive. As a result, the initial fiscal cost can exceed the immediate increase in spending.
Benefits, targeted transfers, and aid to local governments
Payments to households facing income losses can protect essential spending. Temporary transfers may reach liquidity-constrained recipients faster than a newly designed capital project. In addition, support to regional and municipal budgets can reduce pressure to cut existing services as tax revenues fall.
Consequently, targeting matters. A payment to a household struggling to cover rent or groceries may enter local demand quickly. By contrast, support to a recipient with comfortable savings might mainly strengthen its balance sheet. Yet targeting can introduce verification costs and exclude people who lack complete records. Policymakers must balance delivery speed with accuracy and fairness.
| Instrument | Immediate channel | Main practical limitation | Potential longer-term effect |
|---|---|---|---|
| Public purchases | Orders for goods and services | Supplier and labor capacity | Usually limited unless services improve productivity |
| Infrastructure investment | Construction contracts and payroll | Planning, procurement, and completion delays | May raise productive capacity |
| Temporary tax rebate | Higher disposable income | Recipients may save or repay debt | Typically limited after the rebate ends |
| Investment tax incentive | Lower after-tax investment cost | Firms still require profitable projects | Can expand private capital stock |
| Income support | Protection of household cash flow | Eligibility and payment administration | Can reduce hardship and disruption |
| Transfers to local governments | Support for existing services | Restrictions on how funds may be used | May protect public-service continuity |
Automatic Stabilizers Versus Deliberate Stimulus
Budget deficits sometimes rise without new stimulus legislation. During downturns, tax revenue falls and more households qualify for existing benefits. Economists call these automatic fiscal stabilizers because they operate without a new law.
In its November 2024 assessment, the U.S. Congressional Budget Office estimated that automatic stabilizers increased federal deficits by an average of 0.4% of potential GDP each year from 1974 through 2023. That figure describes a long historical average, not a fixed annual effect. During the severe 2020 downturn, CBO’s separate October 2022 analysis estimated that automatic stabilizers added 1.6% of potential GDP to the deficit, followed by 1.3% in 2021.
Furthermore, those estimates distinguish the budget’s reaction to the economy from decisions made through new legislation. For example, emergency enhancements to unemployment benefits enacted in a crisis are discretionary policy, even if existing unemployment programs already act as stabilizers.
How the Fiscal Multiplier Works
The fiscal multiplier describes how much real economic output changes in response to a specified change in government spending or taxation, over a defined period. For a spending increase, a simplified expression is:
Spending multiplier = change in real GDP ÷ initial change in public spending.
Suppose a government raises purchases by $5 billion and the measured increase in real GDP over the selected horizon is $6 billion, relative to a valid no-policy baseline. The implied multiplier is $6 billion ÷ $5 billion = 1.2. This is a hypothetical arithmetic example, not an estimate for a particular country.
A multiplier above one can arise when initial recipients spend part of their income and induce further production. However, leakages through saving, imports, taxes, and higher prices weaken that process. The central bank’s response also matters. If inflation rises and interest rates increase, private borrowing and investment may fall, offsetting part of the fiscal expansion.
Why multiplier estimates differ
Researchers must estimate what the economy would have produced without the policy. That counterfactual cannot be observed directly. Consequently, results depend on the model, time horizon, spending category, recession severity, exchange-rate regime, and other assumptions.
Multipliers may become larger when the economy has significant idle capacity and monetary policy can remain supportive. By contrast, a stimulus delivered into an economy operating near full capacity may produce more inflation or displace other spending. Import-intensive purchases can also send part of the demand abroad.
Consider the same $5 billion purchase under three illustrative multipliers:
| Assumed multiplier | Illustrative change in real GDP | Interpretation |
|---|---|---|
| 0.5 | $2.5 billion | Strong offsets or leakages |
| 1.0 | $5.0 billion | One-for-one measured output response |
| 1.5 | $7.5 billion | Additional rounds of demand dominate offsets |
These figures describe changes in output, not a return on investment or additional tax revenue. Nor does a multiplier of 1.5 prove that borrowing $5 billion will reduce public debt. The financing cost, tax receipts, output persistence, and initial debt position must be considered separately.
What Institutional Research Shows About Fiscal Stimulus
Public investment can be powerful under specific conditions
The International Monetary Fund’s October 2020 Fiscal Monitor assessed a coordinated increase in public investment during the pandemic recovery. Under the report’s modeled conditions, a public-investment increase of 1% of GDP across advanced and emerging market economies had the potential to raise output by 2.7% and private investment by 10% within two years.
The same analysis estimated that the investment push could create approximately 7 million direct jobs and 20–33 million jobs in total when indirect effects were included across those economies. Importantly, the estimates were conditional on investment quality, available financing, high uncertainty, and the private sector’s response. They were scenario-based estimates, not jobs subsequently counted at construction sites.
Consequently, this distinction matters when readers encounter a headline claiming every infrastructure dollar creates a fixed number of jobs. The IMF findings support the potential of well-designed investment in a particular environment; they do not establish a universal conversion rate for all governments, sectors, or years.
Execution quality can matter as much as the budget envelope
A separate IMF policy paper, Making Public Investment More Efficient (2015), compared infrastructure inputs with coverage and quality across countries. The researchers identified an average public-investment efficiency gap of roughly 30%. They also reported that the most efficient public investors received about twice the growth effect per investment dollar of the least efficient.
That is an unusual but practical finding: a larger construction budget is not automatically better fiscal stimulus. Weak project selection, repeated contract changes, delayed land access, and underused assets can consume money without generating the intended services. Moreover, rushed procurement may raise costs precisely when policymakers want fast support.
Historical evaluations contain meaningful uncertainty
Consider the American Recovery and Reinvestment Act of 2009. In a February 2013 report, the U.S. Congressional Budget Office estimated that the law raised real GDP in the fourth quarter of 2012 by approximately 0.1%–0.6% compared with what would otherwise have occurred. CBO also estimated that it lowered the unemployment rate by 0.1–0.4 percentage points that quarter.
These were modeled estimates, not direct measurements of an alternate economy. CBO used recorded spending and tax changes, earlier empirical evidence, and economic models to construct its range. The range itself conveys uncertainty. Furthermore, the figures refer specifically to late 2012, not the package’s peak effect or its lifetime contribution.
Therefore, a thoughtful fiscal analysis should present the evaluation period, the counterfactual method, and the uncertainty range. Quoting one preferred number without those details can make fiscal policy appear more predictable than research supports.
Timing: Fast Cash Support Versus Slow Capital Projects
In practice, a stimulus package has four clocks: authorization, delivery, private response, and the full output effect. The spending schedule often matters more than the announcement date.
For example, a transfer through an existing payment system may support vulnerable households relatively quickly. In contrast, a new transport corridor may require years of design and construction. Meanwhile, maintenance work with approved designs can begin sooner than either a complex new rail line or an entirely new industrial policy.
Timing should also reflect the broader business cycle phases. A project intended to counter a recession may start construction during the next expansion. If labor and materials are scarce by then, late spending could intensify price pressure instead of filling unused capacity.
A delivery test before approving stimulus
For each measure, fiscal planners should identify the recipient, the payment channel, the earliest realistic disbursement date, the capacity constraint, and the condition that ends support. These details often reveal weaknesses that a high-level multiplier estimate will miss.
| Question | What to verify | Warning sign |
|---|---|---|
| Can funds move quickly? | Existing legal authority and payment systems | Long procurement or new eligibility platform |
| Will recipients spend? | Liquidity needs and near-term demand | Most money likely held as savings |
| Can suppliers deliver? | Labor, materials, and productive capacity | Backlogs and sharply rising bids |
| Will benefits persist? | Project use, productivity, and maintenance | Asset with weak demand or no upkeep funding |
| Can support end? | Sunset provisions and exit procedures | Temporary benefit becomes permanent by default |
Inflation, Crowding Out, and the Supply-Side Limit
Importantly, expansionary measures raise demand most safely when firms can increase output without severe bottlenecks. During a recession, idle machinery and unemployed workers may allow production to respond. However, during an energy shortage or other supply disruption, businesses may not be able to supply much more even when consumers have extra cash.
Consequently, broad fiscal stimulus can raise prices rather than output if demand exceeds available capacity. The effect may be concentrated in a few markets: construction wages, rental housing, building materials, or imported equipment.
In addition, higher public borrowing can increase competition for financing. Economists call the resulting reduction in some private investment crowding out. However, that outcome is not inevitable. When unused savings and weak private demand prevail, public investment may instead encourage complementary private projects, sometimes called crowding in.
For households, inflation can offset an apparent rise in nominal income. A payment of $500 does not deliver the same real purchasing power if prices have already increased significantly. Analysts should therefore calculate the inflation rate and examine real wages, real consumption, and purchasing power alongside headline spending.
Debt Sustainability: What a Government Must Finance
Expansionary fiscal policy often widens the budget deficit in the near term because spending increases or tax receipts decline. Yet the size of the deficit alone does not determine whether a policy is affordable. Debt sustainability depends on the existing debt burden, average borrowing cost, economic growth, refinancing exposure, currency composition, and credibility of future budgets.
For example, a government that borrows at relatively low long-term rates to replace a failing power grid may improve productivity and future revenues. Another government may struggle to refinance short-maturity foreign-currency debt even when its planned stimulus is modest. The same percentage-of-GDP package can therefore carry very different risks.
A simple debt-service illustration helps separate cash flow from economic benefit. Suppose a government issues $10 billion of new debt at a fixed 4% annual coupon. Interest payments would be approximately $400 million per year, excluding issuance costs, tax effects, maturity repayments, and refinancing. The calculation does not tell us whether the program is worthwhile; it identifies one obligation that its benefits must be assessed against.
Nevertheless, borrowing can be defensible when the policy prevents lasting economic damage or finances productive assets. However, repeated support without a credible financing plan can raise risk premiums and eventually constrain future crisis responses. Good fiscal design therefore includes an exit path, medium-term projections, and explicit acknowledgment of downside scenarios.
Where Stimulus Programs Fail in Practice
Failure 1: Announcing support that arrives after the shock
A package may pass legislation quickly yet distribute funds slowly. Households and businesses cannot spend resources they have not received. Policymakers should publish disbursement milestones and use delivery channels that already work wherever possible.
Failure 2: Treating a tax cut as guaranteed consumption
A household can save a rebate or pay down debt. Those decisions may improve resilience without delivering a large immediate demand response. Analysts should consider recipient liquidity, household debt, and the expected share spent within the relevant period.
Failure 3: Mistaking higher construction costs for stronger growth
Rising bids may signal scarce workers and materials rather than productive expansion. If project costs jump while output remains unchanged, the program may deliver less infrastructure for the same public money. Competitive procurement and realistic schedules help contain that risk.
Failure 4: Using stimulus after the economy has recovered
Support that continues during an expansion can add inflation pressure and complicate monetary policy. Consequently, temporary programs need expiry rules or clearly defined review dates. Permanent changes should be justified through a separate structural-policy assessment.
Failure 5: Ignoring maintenance and long-run liabilities
A newly built asset creates future obligations. A bridge that lacks maintenance funding may deteriorate before generating its full value. Similarly, recurring subsidies can outlast the emergency that prompted them. Project appraisal should include lifetime costs, not merely construction spending.
How to Evaluate a Proposed Fiscal Stimulus Package
Readers can apply a disciplined five-step test to policy announcements. First, identify the economic problem. Weak demand, a credit crisis, an energy shortage, and a natural disaster require different interventions. Second, separate the approved amount from the likely near-term cash outlay. Third, map the mechanism by which recipients would spend or invest the money.
Fourth, examine capacity and inflation risk in the sectors receiving support. Fifth, review debt financing and the strategy for ending the program. This approach is more revealing than ranking packages by their headline size alone.
| Economic situation | Potential fiscal priority | Why caution remains necessary |
|---|---|---|
| Demand-led recession with idle capacity | Temporary income support and deployable investment | Delivery lags and debt constraints |
| Supply shortage with high inflation | Targeted hardship protection and supply repairs | Broad transfers may amplify price pressure |
| Financial crisis with frozen credit | Temporary guarantees and targeted stabilization | Contingent liabilities and moral hazard |
| Slow growth from weak infrastructure | Well-appraised productivity investment | Construction delays and execution efficiency |
| High debt and expensive refinancing | Prioritize high-impact, affordable measures | Loss of financing access or market confidence |
Frequently Asked Questions
What is an example of expansionary fiscal policy?
An example is a temporary increase in government spending, a tax rebate, or expanded income support intended to strengthen demand during a downturn. The economic effect depends on how promptly the measure is delivered and how households or firms use the resources.
Does expansionary fiscal policy always increase inflation?
No. Fiscal expansion can increase real output when workers and businesses have spare capacity. Inflation risk rises when extra demand meets limited supply or when the central bank responds with tighter financing conditions.
Are tax cuts or government spending more effective?
Neither instrument is always superior. Purchases create direct demand, while tax cuts influence private behavior. Their relative effect depends on timing, recipient incentives, the economic cycle, administrative capacity, and the chosen evaluation horizon.
What is the difference between automatic stabilizers and discretionary fiscal stimulus?
Automatic stabilizers change taxes and existing benefits as the economy changes, without new legislation. Discretionary stimulus requires a new policy decision, such as an emergency rebate, additional public purchases, or a temporary spending program.
Can fiscal stimulus reduce public debt?
Stimulus may improve the debt-to-GDP ratio if it supports enough durable growth, but that outcome is not guaranteed. Governments must also finance the initial deficit, service debt, manage refinancing risk, and evaluate whether the output gains persist.
The Bottom Line
Expansionary fiscal policy can protect incomes, support employment, and stimulate investment when private demand falls. However, budget size is only one part of the story. The evidence from the IMF and the Congressional Budget Office shows why delivery quality, automatic stabilizers, economic conditions, and estimation uncertainty deserve equal attention.
For a credible assessment, separate temporary demand relief from long-term productive investment. Then evaluate the program’s actual payment schedule, spending response, inflation exposure, and fiscal cost. That produces a more useful judgment than assuming either that all government spending is wasteful or that every stimulus dollar multiplies into guaranteed growth.